
Unit II - Break-Even Analysis


Concept of Break-Even Analysis:

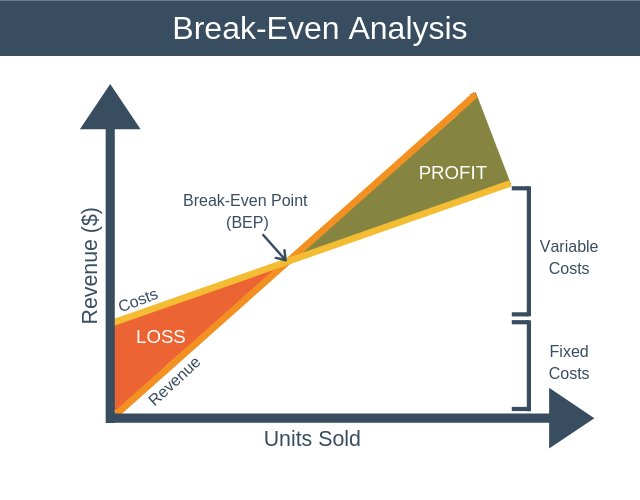
Break-Even Analysis is a concept used very widely in production management and cost. It is an analytical tool which helps the firm to identify that level of sale where it will cover its cost of production. Any sale over and above the break- Even Point will accrue profits to the firm, while any sales less than it would put the firm into losses. The Break-Even Point shows the price at which the firm makes neither profit nor loss. Break-Even point is a very significant concept in Economics and business, especially in Cost Accounting. Break-Even point is a point where the cost of production and the revenue from sales are exactly equal to each other; which means that the firm has neither made profits nor has incurred any losses. The Break-Even Analysis is also known as the Cost- Volume- Profit Analysis and is used to study the relationship between total cost, total revenue, profits and losses. It also helps to determine that level of output which is required to cover the operating costs of a business.

Limitations of Break-Even Analysis:

For the break- even point to be counted, all costs need to be clearly categorized in fixed and variable costs, which may not be possible every time.
For the multiple- product or joint- product operations, it is difficult to apply the break-even analysis. on needs to ascertain the costs to each product, hence the analysis is applicable only for a single product.
The computation of the break-even point is based on the historical information. If this information is not relevant, the analysis cannot be applied usefully.

Significance of Break-Even Analysis:

The break-even analysis helps us to determine the levels of sales necessary to meet all the operating costs. With the estimates of revenue and costs, we can forecast the profits. One can also appraise the effects of change in price, fixed costs and variable cost on sales volume, total cost and total revenue and in turn, on the break-even point. One can compare the profit earning capacities of different firms. It can also bring out the significance of capacity utilization for achieving economy.

Video Lecture Links:


Contents   1   2   3   4   5

Comments

Popular posts from this blog

PROSE 2 - Mallika Srinivasan

SUMMARY Life History Born on November 19, 1959, as the eldest daughter of industrialist A Sivasailam, she is the pride of her parents. She was always brilliant in academics. She did her in MA (econometrics) from Madras University. Thereafter, she went abroad to pursue further studies. She did her MBA from the Wharton School of the University of Pennsylvania. Married to Venu Srinivasan, the CMD of TVS Motor, she is living happily with their two children. In the year 1986, she planned to join the family business. She was made the General Manager of Tafe (Tractors and Farm Equipment) Company. When she took over the responsibility of furthering the economic wealth and business, the turnover of the Company was Rs 85 cr. Under the expert guidance of her father and the wholehearted support of the team, she brought about a major transformation. She converted Tafe into a hi technology-oriented company, thereby becoming the initial choice of the farmers. There was a period, when the...

Unit I - Management Accounting

1. Management Accounting: Management Accounting: Meaning, Nature, Characteristics, Objectives, Advantages and Limitations   Meaning of Management Accounting: The term Management Accounting consists of two words “Management” and “Accounting”. It is the study of managerial aspects of accounting. It is a tool in the hands of management to exercise decision making. The emphasis of management accounting is to redesign accounting in a manner which is helpful to the management in framing the policies and control of their execution. Management accounting is of recent origin. The term was first used in 1950 by a team of accountants visiting the U.S.A. under the auspices of Anglo-American Council on productivity. The terminology of cost accounting had no reference to the word ‘management accountancy’ before the visit by this study group. Intensive competitions, large scale production, dynamic developments in technology, and complexities of modern business have led to the deve...

Phrose 1 - The Town Week - by E.V. Lucas (Sem IV)

In his celebrated essay, “The Town Week” E. V. Lucas very artistically painted various moods and attitudes of the urban people in the seven days of a week. On Monday, people wake up from their dreamy and lazy languor. The day seems flat as if without any colour and flavour. The fun and relic of the Saturday and Sunday have gone. They look morose and pale. A dull and monotonous life is going to eat them up once again. Reluctantly, people come back to their workplaces from their village home. The town becomes populated and busy. The local trains are over-crowded. They do not put their interest in their work. So, most of the time, they enjoy gossiping with their colleagues about their week-end spending. The laziness of Monday almost dries up on Tuesday. People become more active and exciting like “glittering star”. They take their job more seriously. The day is pretty good for the businessmen. The week looks more stirring and energetic on Wednesday. It is th...